An MGA wants to add windscreen cover to its motor product before the renewal season, and the change waits in a developer queue behind two others, while the policy data it needs is split between an ageing core and a set of spreadsheets. That is where most plans to build insurance policy management software start. A build from scratch spends its first months on what every policy administration system already does, and a closed suite puts each product change on the vendor’s release cycle. Our view, after implementing these systems for insurers, is to configure the standard policy lifecycle on a ready platform and build custom only where your business is different.
What is insurance policy management software?
Insurance policy management software, also called a policy administration system (PAS), is the system of record for every policy an insurer, MGA or broker writes. It holds the policy, its coverages, the customer and the full change history, and it runs the transactions of the policy lifecycle: quote, bind, issue, endorse, renew, cancel and reinstate.
For the business, that means one answer to the questions customers, underwriters, finance and the regulator ask: what is covered, since when, at what premium, and who changed it. When the answer lives in three systems and a spreadsheet, every renewal and every audit starts with someone reconciling them.
Policy administration also feeds the work around it. Rating and underwriting set the price and decide whether to accept the risk, billing collects the premium, claims pays out against the cover in force on the day of the loss, and reporting tells management how the book is doing. A modern PAS either includes these functions or connects to them through APIs, the interfaces that let two systems exchange data without anyone re-keying it. Our guide to insurance software describes each of these types in more detail.
A next-gen, flexible technology foundation in policy management is mandatory, enabling insurers to adopt new trends like GenAI, AI, and embedded insurance to accelerate changing the business to meet modern era demands.
Michał Głomba, CEO, Stratoflow
How a policy administration system works day to day
The quickest way to understand a policy administration system is to follow one policy through it.
From submission to quote
An agent, a broker or the customer enters the client’s details and the risk (a property, a fleet, a trip) once, through a form or a partner’s website. The system applies the product’s rating tables and underwriting rules to that data: straightforward risks are quoted automatically, and unusual ones are referred to an underwriter with everything needed for the decision on one screen.
The quote goes to the client from the system itself, so no version of the proposal sits in a mailbox that the policy record does not know about.
From a bound policy to the renewal
Once the client accepts, the quote becomes a policy, and the schedule, certificate and wording are generated from templates. Mid-term changes are endorsements: the system re-rates only the change, charges or refunds the pro-rata premium and records who changed what. Renewal offers go out on schedule, and an account handler gets a task only where judgement is needed.
Claims and billing on the same record
When a loss is reported, the claim is opened against the policy, so the handler sees the cover and limits that applied on the date of the loss. Instalments, payments and outstanding balances sit on the same record.
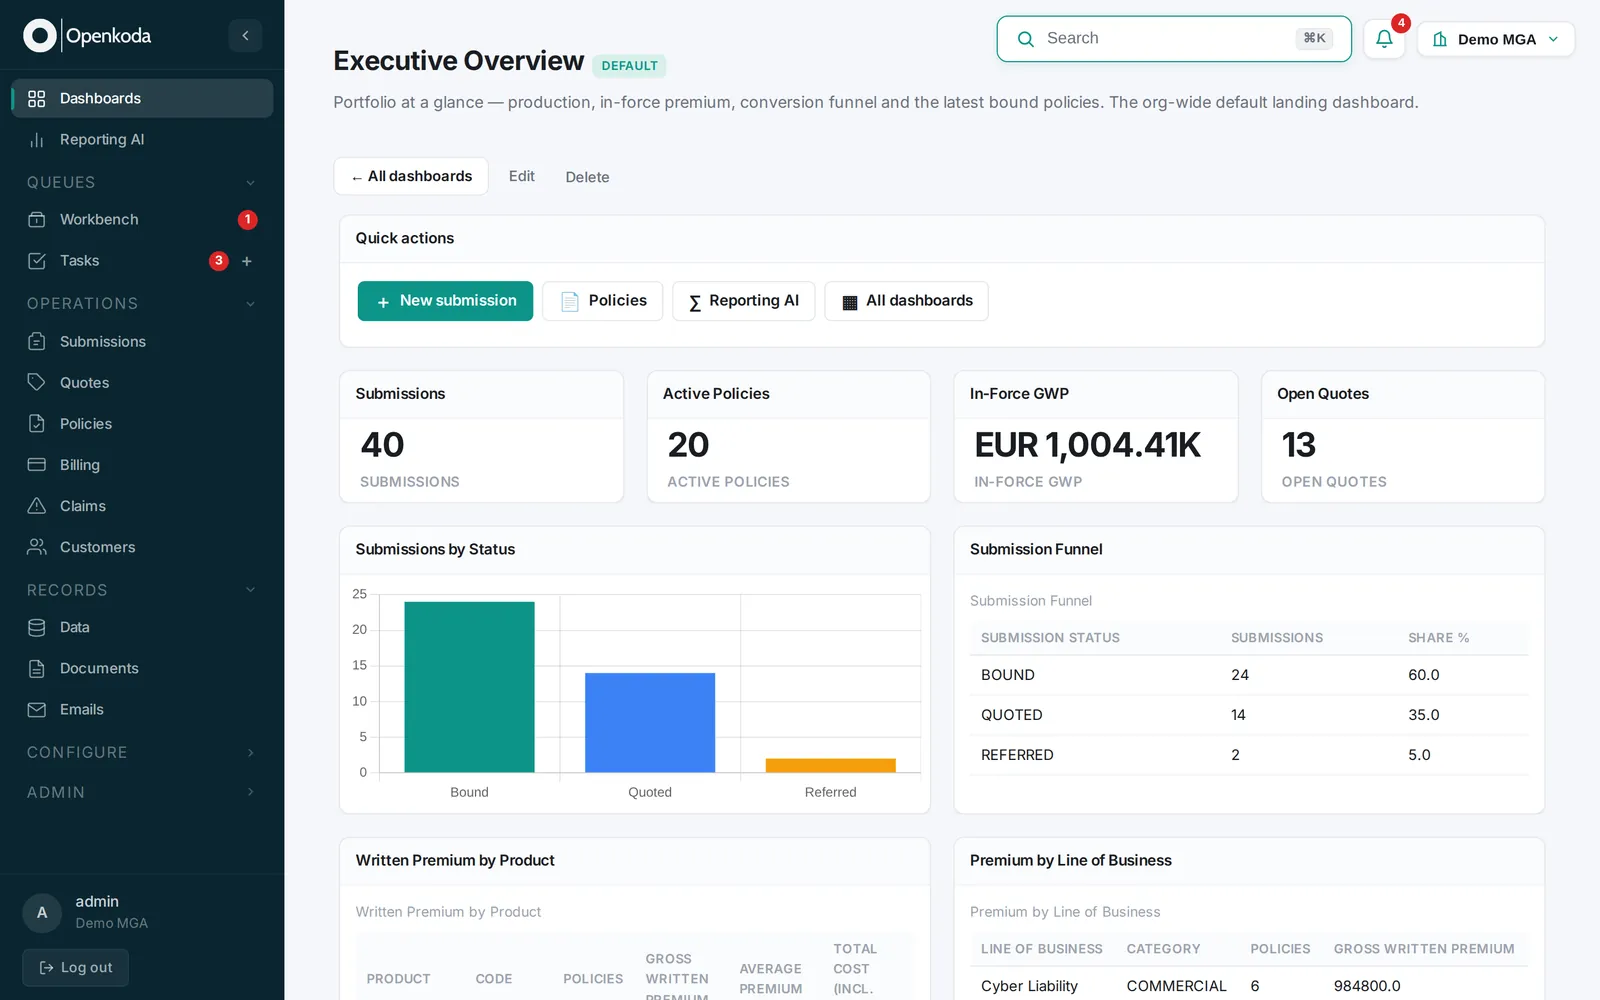
Because everything is in one place, managers can see submissions, conversion, premium in force and open claims on a dashboard instead of waiting for someone to export and merge spreadsheets.
Key features of an insurance policy administration system
Every PAS vendor publishes a feature list. These are the eight features we check first when an insurer asks whether a system will carry its book, with what each one changes for the business.
Policy lifecycle
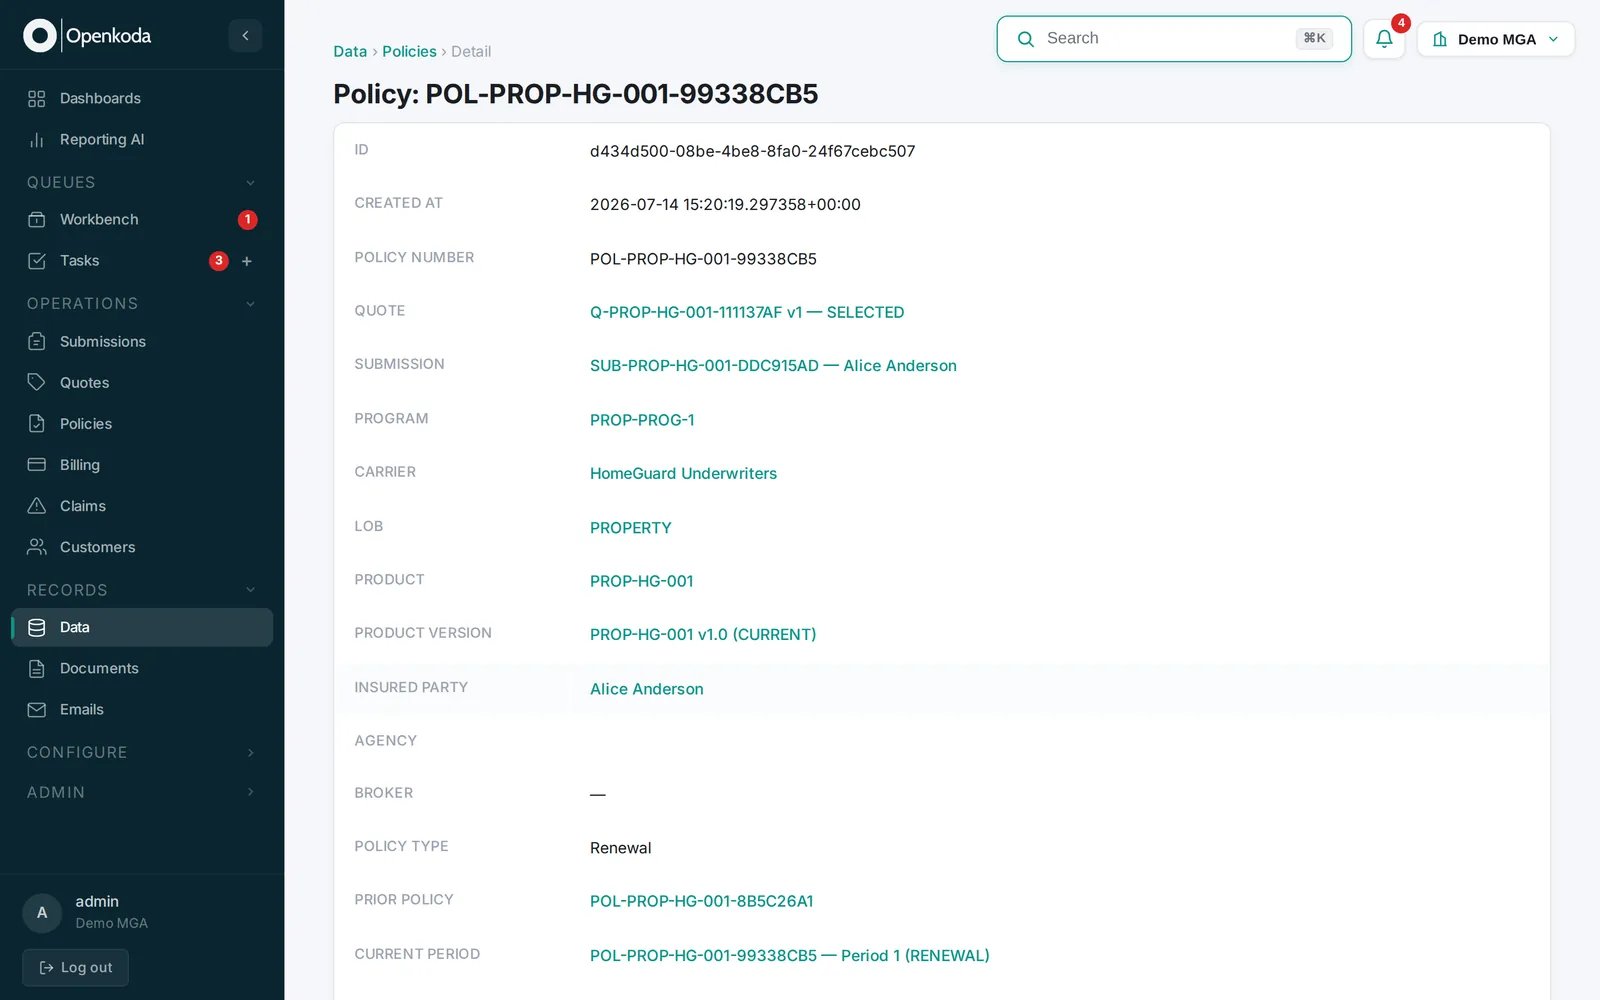
New business, endorsements, renewals, cancellations and reinstatements on one record, each going through the same workflow. Ask about product versioning: when a product changes, policies already in force should stay on the version they were bound under, so what a customer was covered for last March is still on record after the change.
Product configuration
Launching a product or changing a rate should be configuration that a product manager or underwriter prepares and someone else approves, not a development project. In a demo, ask the vendor to add a coverage, a rating factor and an underwriting rule, and to show how long the change takes to reach production.
Workflow automation
Renewal reminders, referrals, approvals, document runs and notifications should follow rules that the business can change itself. Every step the system takes over is one an account handler no longer does by hand at the end of the month.
Claims and payments
First notice of loss, reserves, approvals and payments on a configurable workbench, and premium collection with instalment plans and automatic reminders for overdue payments. Fraud checks from specialist providers can connect through the system’s APIs instead of being rebuilt inside it.
Reporting and AI
Managers need loss ratios, conversion, premium in force and claims trends, each view set up for a role. Newer systems add AI reporting: you ask a question about the book in plain English (which products grew this quarter, what retention looks like) and get a report back, without learning a query language or waiting for the analytics team.
Document generation
Policy packs, schedules, certificates and endorsement documents produced from templates with the policy’s own data, in your brand, and stored against the record they belong to.
Compliance and audit
A full audit trail of who did what and when, role-based access so each user sees and changes only what their role allows, and the reports your regulator and partners expect, such as bordereaux, the premium and claims reports an MGA owes its carriers under delegated authority. Regulations change, so the rules in the system have to be changeable without a rebuild.
Integrations
Payments, accounting, CRM, rating bureaus, data providers and partner websites all exchange data with the PAS. Look for documented REST APIs, webhooks (messages the system sends when something happens, such as a policy being bound) and an API that lets a partner’s website quote and bind directly, for example through an embedded quote form.
Custom vs out-of-the-box insurance management software
When choosing a policy management system, most insurers start from two options: buy a packaged product, or have one built.
Out-of-the-box software
Packaged insurance software is quick to set up and costs little at the start. The trouble begins when your process does not match the vendor’s. Say you need a quote form that partners can embed on their own websites: if the product has no such feature, you wait for the vendor’s roadmap or pay for a change.
Pros
- Quick setup on a proven product.
- Vendor support and a user community.
- Low initial cost.
Cons
- Customization limited to what the vendor exposes.
- Changes and integrations depend on the vendor.
- Vendor lock-in: your data and processes are hard to move.
Custom software
A custom build fits your processes exactly, and you own the code and the data. The price is paid up front, in money and in time before the first policy is issued, because the team spends its first months building what every PAS already has: policy records, endorsements, versioning, documents and user roles.
Pros
- Scales with your book on your terms.
- Lower long-term costs, with no licence fees.
- Complete ownership and control.
- Data protection designed around your own policies.
Cons
- Higher initial investment.
- Longer development time before the first policy is issued.
What a custom build from scratch costs
These are our estimates for a policy management system built from scratch: the team, the budget and the time to a working system, by project size.
A third option: configure a policy administration system
Between the two sits a configurable PAS. The policy lifecycle, rating, documents and audit trail work on the first day, and your products, rules and workflows are configured on top. Custom development is kept for the parts where your business is different, such as a proprietary rating model or an unusual claims process.
A customizable system like Openkoda empowers insurance companies to tailor products to their unique needs, ensuring better alignment with business goals. It also enables continuous development, allowing insurers to adapt to evolving industry trends and maintain a competitive edge.
Michalina Stark, Business Analyst, Stratoflow
How to build an insurance policy administration system in 5 steps
The steps below are how a deployment of Openkoda, the platform we implement most often, runs. Openkoda is an insurance policy administration system that insurers configure with AI, from quote to claim: rating, underwriting, policy administration, claims, billing, workflow automation, document generation and bordereaux reporting for delegated authority. It is built and licensed by our sister company of the same name; Stratoflow is the implementation partner.
The platform runs fully managed on Openkoda Managed Cloud or on premise in your own infrastructure, on a subscription licence, and your configuration and data stay yours. According to openkoda.com, an implementation takes weeks to a few months, depending on scope.
Step 1: configuration analysis
It starts with a thirty-minute scoping call and a written ballpark from us: which of your products and integrations the platform covers, which custom modules you need, and what it costs. Then comes the configuration analysis, in which your team and the implementers model your products, pricing, rules and workflows together.
Openkoda includes the first five professional-services days of that analysis in every plan, according to its pricing page. A full implementation takes longer, and the work beyond those days is scoped and billed on time and materials.
Step 2: product configuration
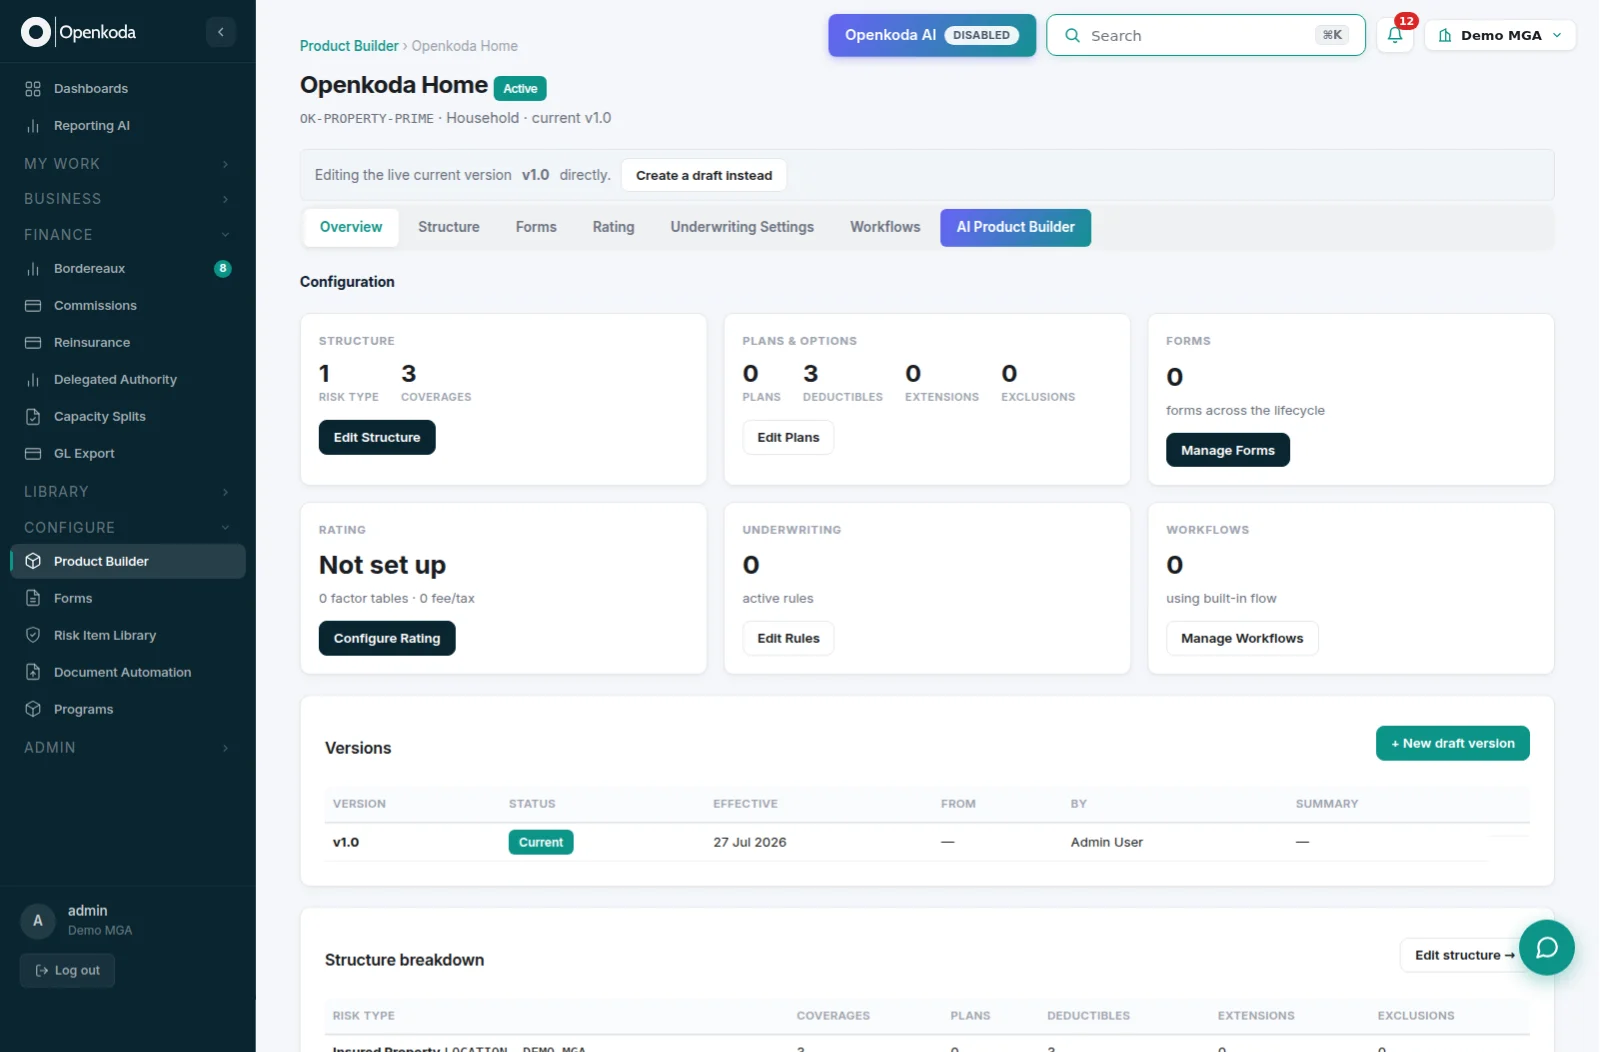
Coverages, limits, rating tables, underwriting rules, forms and workflows are configured on the platform rather than coded. With the AI Product Builder, a product manager describes a change in plain English (add windscreen cover to motor and re-rate it) and the AI drafts it as a list of specific changes, drawn from a fixed catalogue of operations and never free-form code. A person reviews the before-and-after and approves it; nothing is applied until then, and every change is versioned and recorded in the audit trail.
Each product version moves from Draft to Current to Superseded, and policies in force stay on the version they were bound under.
Step 3: integrations
Openkoda connects to accounting, payment, reinsurance, document and distribution systems through REST APIs, webhooks and a submission API on every form, so a partner’s website can quote and bind directly. Its MCP server (a standard way to connect AI assistants to business systems) lets an assistant such as Claude work with the live book under each user’s own permissions, with every write confirmed by the user and audited.
Whatever the platform does not cover, we build as custom modules in Java and Spring; the engineers who write them are the ones who configure the platform.
Step 4: data migration and parallel run
Policies, claims and their history move to the new system with versioning intact, so what the cover was on a given date still has an answer after the switch. The old and new systems then run side by side until the differences are reconciled and your team trusts the new one.
Step 5: go-live, managed or on premise
The cutover comes with a tested rollback. On Openkoda Managed Cloud, Openkoda hosts, monitors, backs up and upgrades the platform with SLA-backed support. On premise, the platform is installed in your own environment and region, and you decide when to take upgrades. From the first day, managers work from dashboards built on live policy data.
After go-live: support and changes
Product changes continue the same way after launch: configured, approved and versioned. We run the custom modules and integrations under a managed support retainer, or hand them over to your team with documentation and knowledge transfer.
Example: Core Travel Insurance, live in eight weeks
Core Travel Insurance, a group travel insurer, went from contract to a live policy platform on Openkoda in eight weeks in 2026. Our implementation configured its travel products, rates and rules, integrated its payment and document systems and migrated its existing clients, with the portals delivered in the same eight weeks. SkyGuard, a life and aviation specialty insurer, runs its policy administration on the same platform (case study).
In Openkoda’s Policy 360 demo, a live policy is shown on one screen, and a new action is added to it while the system is running.
Top 5 insurance policy administration software in 2026
We checked each of these systems on its vendor’s website in October 2026; customer counts and timelines are the vendors’ own figures. Openkoda is built by our sister company, so read its entry with that in mind. For the larger core suites, see our guide to insurance core systems.
Openkoda
Openkoda is an insurance policy administration system configured with AI, covering the lifecycle from quote to claim for insurers, MGAs, brokers, TPAs and insurtechs, in P&C and life. It runs fully managed or on premise, and its plans are published flat annual contracts with no per-seat, per-policy or percentage-of-premium fees.
Top features
- AI Product Builder: products and changes described in plain English, drafted as reviewable changes, approved by a person, versioned and audited.
- Quote to claim on one platform: rating, underwriting, policy administration, claims, billing, documents and bordereaux for delegated authority.
- Reporting AI for questions about the book in plain English, and an MCP server for AI assistants working with live data under each user’s permissions.
- Multi-tenant, multi-brand and multi-currency, on an ACORD-aligned data model (ACORD sets the insurance industry’s data standards).
Best for
MGAs, carriers, brokers with delegated authority and TPAs that want to change products themselves, keep ownership of their configuration and data, and choose between a managed service and their own infrastructure.
Decerto Policy Administration System
Decerto’s Policy Administration System is built from four modules (Policy Processor, Policy Register, Policy Service and Payment) that can be deployed together or one at a time, each configured for life insurance, P&C or both. Its event-driven architecture records every action on a policy as an event, which gives a complete change history and makes every step of policy processing traceable.
Around the PAS, Decerto sells the Higson product configurator, an underwriting workbench and a self-service customer portal, and in 2026 it markets mainly to US P&C carriers, MGAs and TPAs. Decerto puts its median time from contract to a first working configuration at four to six weeks.
Top features
- Four modules, deployed together or individually, for life, P&C or both.
- Event-driven processing, with log entries sent to the subledger for traceability.
- Higson product configurator for coverages, options and rating rules without coding.
Best for
Life and P&C insurers that want to replace their policy administration one module at a time, starting with the most pressing problem, with a vendor that also builds custom software around it.
Guidewire InsuranceSuite
Guidewire InsuranceSuite is a set of core applications for P&C insurers: PolicyCenter, ClaimCenter and BillingCenter, now joined by PricingCenter and UnderwritingCenter, available individually or as a bundle and run on Guidewire Cloud. Guidewire counts more than 300 P&C customers worldwide. For smaller carriers, it sells InsuranceNow as a separate all-in-one cloud core.
Top features
- Policy, claims and billing applications that share one data model.
- Pricing and underwriting in the suite through PricingCenter and UnderwritingCenter.
- The Guidewire Marketplace of pre-built partner integrations, and a large network of certified implementation partners.
Best for
Large and mid-size P&C carriers with complex, multi-line portfolios and the budget and partner capacity for a large implementation programme.
BriteCore
BriteCore is a cloud-native core platform for P&C insurers and MGAs, delivered as SaaS, with policy administration, billing, claims, reporting, and agent and policyholder portals. In 2026 it leads with AI: copilots and multi-agent systems built into underwriting, claims and billing workflows with a person kept in the loop, and published APIs and MCP tools for carriers and partners connecting their own AI agents. BriteCore says it serves more than 100 insurance clients across the US.
Top features
- Policy, billing and claims with agent and policyholder portals on one data store.
- AI copilots built into underwriting, claims and billing.
- Persona-based dashboards and a library of standard reports.
Best for
Small and mid-size US P&C carriers and MGAs that want a SaaS core with AI built in and no upgrade projects.
Sapiens
Sapiens sells the Sapiens Insurance Platform, with a core suite for each sector (IDITSuite for P&C and CoreSuite for life and pensions) plus DigitalSuite for portals and digital engagement, DataSuite for analytics, decision management and reinsurance. Sapiens describes the P&C platform as modular SaaS with AI-powered automation and low-code configuration tools, and reports more than 600 customers in 38 countries.
Top features
- Separate cores for P&C (IDITSuite) and for life and pensions (CoreSuite) on one platform.
- Pre-configured business packages for P&C lines, including commercial and specialty.
- Recognised by the analyst firm Celent in 2025 for policy administration in P&C (EMEA and APAC) and in life (EMEA).
Best for
Insurers that write both P&C and life or pensions business across several countries and want one vendor for both cores.
Build, buy or configure: which route fits your business
A packaged suite is the right answer for a large P&C carrier with a multi-line book and the budget for a long programme, and we say so when it is. A build from scratch makes sense when the product itself is the business and no platform’s policy model fits it.
For most MGAs, specialty insurers and brokers with delegated authority, configuring a PAS and building only the differences gets products live in weeks to a few months, with the configuration and data still theirs. Openkoda is not the answer for every insurer either, and much of our insurance work is integration on the core an insurer already runs.
If you are weighing these routes, a thirty-minute scoping call with us ends with a written ballpark for your case.